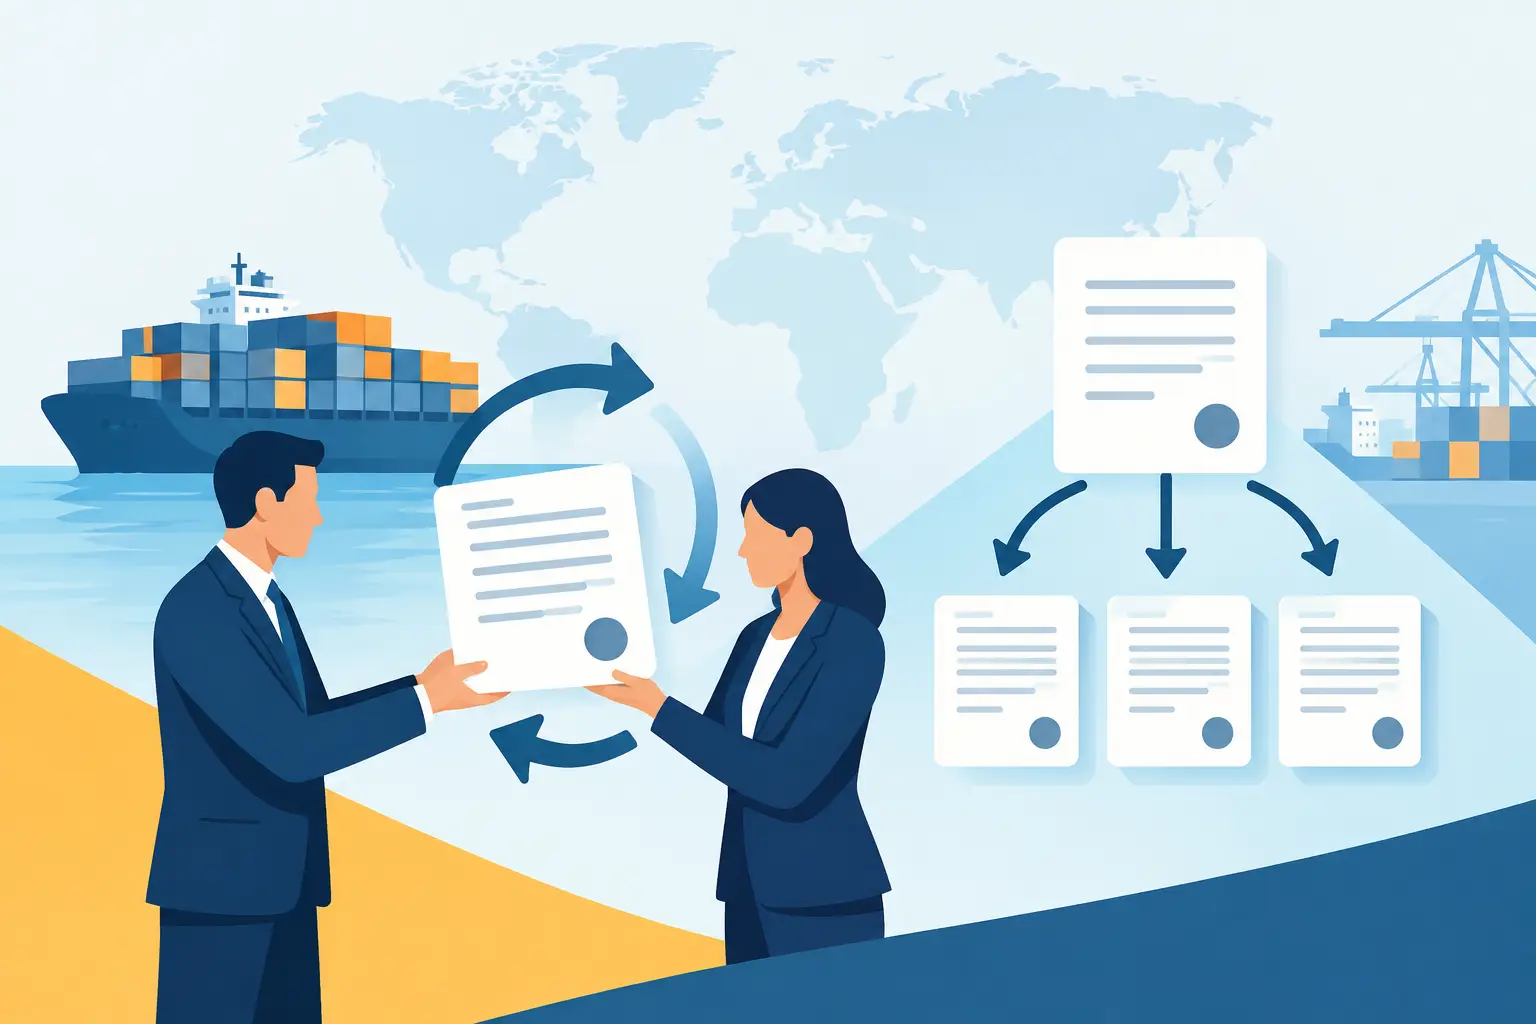
A letter of credit can make an overseas sale bankable, but only when its terms match the way the goods are actually bought, supplied and shipped. “Transferable and divisible L/Cs explained” is therefore not merely a banking question. It concerns the practical relationship between buyer, exporter, supplier and bank – and the point at which an intermediary may be paid without exposing either party to an unnecessary risk.
The terminology is often used loosely. A transferable credit has a precise meaning under the rules normally governing documentary credits. A divisible credit, by contrast, is not generally a formal category in the same sense. People may mean that the credit can be split between suppliers, that partial shipments are permitted, or that the proceeds may be shared. Those are different arrangements, with different consequences.
Back in the 1970s, I built a business using transferable and divisible letters of credit to assemble package deals for major contractors throughout the Middle East. These included projects such as Doha General Hospital, Salmaniya Medical Centre, the Kuwait Water Towers and the Aqaba Holiday Inn, along with numerous others across the region. The contractor placed a single order with my company, and I brought together products from numerous manufacturers, arranging for them to be shipped as one consignment. Without these two ingenious banking arrangements, I simply would not have had the financial resources to undertake such contracts. They enabled a small export merchant with limited capital to compete for substantial international business that would otherwise have been beyond his reach.